Calculating Quarterly Estimated Taxes 2026: A Realtor's Form 1040-ES Walkthrough
This is education, not tax advice. I'm not a CPA or EA. State taxes are not covered.
Form 1040 and Schedule 1 cited below are IRS draft as of 2026-10-06 — DRAFT, NOT FOR FILING. If a line changes, this page is updated in place with a dated note at the foot of the article.
- Last checked
- Tax year
- 2026
- Core line
- Form 1040-ES, line 15
- Changes
- Update log (1)
Each 2026 estimated tax payment is Form 1040-ES line 15: the amount on line 14a divided by four. The four due dates are April 15, June 15, September 15, 2026, and January 15, 2027, and all four payments are claimed on Form 1040, line 26.
§1One job, one tax year, one line
The job is real estate agent, first year on a 1099 instead of a W-2. The year is 2026. And the line this article locks onto is not on the return you file next spring — it is on the worksheet you use during the year, Form 1040-ES, line 15: the amount of each estimated tax payment. By the end, you will see where that number comes from, the four dates it is due, and the one line on Form 1040 where all four payments land.
§2Where this income lands, and why nobody withholds
A commission check has no withholding taken out of it. That is the whole problem this form exists for.
Here is the path that income takes on paper. Business income is figured on Schedule C. Its net profit, line 31 on the draft, is entered on Schedule 1, line 3 — the line that reads "Business income or (loss). Attach Schedule C."

When an employer paid you, tax was taken out of every check before you saw it. On a 1099, that step does not happen during the year — unless you do it yourself, in four payments, using Form 1040-ES. The form does not ask what you earned. It asks what tax you expect, and it turns that expectation into four payment amounts and four due dates.
§3The four due dates and the $1,000 test
Publication 505, Chapter 2, prints the payment schedule for 2026:
| Payment | Due date | Income period it follows |
|---|---|---|
| First | April 15, 2026 | 3 months |
| Second | June 15, 2026 | 2 months |
| Third | September 15, 2026 | 3 months |
| Fourth | January 15, 2027 | 4 months |
Look at the spacing, because it is not quarterly in the calendar sense. The first period covers three months of income, the second covers two, the third covers three, and the fourth covers four. Three, two, three, four. Hold that pattern — it explains the single most common misunderstanding about this worksheet, in the Fork section below.
Before the dates apply to you at all, the worksheet runs a test, and the test sits on its own line: line 14b. Work up to it the way the worksheet prints it. Line 11c is the tax you expect for 2026 — the worksheet captions it "Total 2026 estimated tax" — and it is reached only after line 11b subtracts any refundable credits from the figure above it. Line 13, further down the page, is income tax withheld: withholding, and only withholding. Line 14b subtracts line 13 from line 11c and asks the question as the worksheet prints it: is the result less than $1,000? If it is, this payment system is not triggered. If it is $1,000 or more, the four dates above are your dates.
§4Worked example: the worksheet, start to finish
One worked example, with numbers used only in this article. Our agent is in her first full year self-employed. These are hypothetical worksheet inputs, not a prediction and not your numbers. She expects her total tax for 2026 to be $20,000. Her 2025 return — a W-2 year — showed tax of $16,500, and her 2025 adjusted gross income was not over $150,000. In 2026 she expects no withholding and no refundable credits.
First, the worksheet's required annual payment — lines 12a, 12b, and 12c. Line 12a is 90 percent of the 2026 tax: 90 percent of $20,000 is $18,000. Line 12b is the prior-year figure: 100 percent of the 2025 tax, which is $16,500. One note the worksheet prints on that line: if 2025 adjusted gross income was over $150,000 — $75,000 if married filing separately — the percentage on line 12b is 110 percent, not 100. Her income was not over that line, so 100 percent stands.
Line 12c takes the smaller of the two: $16,500. That smaller figure is the required annual payment the worksheet works from — the form's own comparison, read as written, not a strategy this site is recommending.
Line 13 is income tax withheld: zero in this example — a stated input. Refundable credits do not sit on this line; the worksheet subtracted them earlier, at line 11b, on the way to line 11c. So line 14a, the amount to be paid in installments, is $16,500 minus zero — $16,500.
Now line 14b — the $1,000 test itself. Line 14b subtracts line 13 from line 11c: $20,000 minus zero is $20,000. The question printed on that line is whether the result is less than $1,000. It is not, so the worksheet goes on to line 15.
Line 15 divides line 14a by four. $16,500 divided by four is $4,125. That is each payment. April: $4,125. June: $4,125. September: $4,125. January: $4,125.
| Step | Worksheet line | Operation | Amount |
|---|---|---|---|
| Refundable credits | Line 11b | Hypothetical input | $0 |
| Total 2026 estimated tax | Line 11c | Expected tax entered on the worksheet, after line 11b | $20,000 |
| 90% of 2026 tax | Line 12a | $20,000 × 90% | $18,000 |
| 100% of 2025 tax (2025 AGI not over $150,000, so not the 110% figure) | Line 12b | $16,500 × 100% | $16,500 |
| Required annual payment | Line 12c | Smaller of 12a and 12b | $16,500 |
| Income tax withheld | Line 13 | Hypothetical input — withholding only | $0 |
| Amount for installments | Line 14a | Line 12c − line 13 | $16,500 |
| $1,000 test | Line 14b | Line 11c − line 13 = $20,000 — not less than $1,000, so the worksheet continues | $20,000 |
| Each installment | Line 15 | Line 14a ÷ 4 | $4,125 |
| Claimed on the return | Form 1040 line 26 (2026 DRAFT) | 4 × $4,125, plus $0 applied from the 2025 return | $16,500 |
§5The Fork: equal payments, unequal periods
The periods are unequal — three months, two months, three months, four months. The payments, under the Regular Installment Method, are not. Publication 505 divides the required annual payment into four equal installments. Line 15 is one division by four, applied four times. A big closing in December does not make the January payment bigger than the April payment under this method, and a slow spring does not make the June payment smaller.
Unequal income timing is handled by a different method, on a different form: the annualized income installment method, on Form 2210, Schedule AI. That method recomputes each period from the income actually earned in that period. Trade Tax Desk reads it in full in the October-starter catch-up article, because it has its own worksheet — Worksheet 2-9 in Publication 505 — and one attachment rule worth stating here: if you used Worksheet 2-9 to figure a payment, Form 2210 goes in with your return. The fork is real, but this article does not pick a winner for you. It reads what each method's lines actually do.
§6Where the payments land: Form 1040, line 26
Fast-forward to the return itself. Every dollar sent with those four vouchers during 2026 is claimed in one place: Form 1040, line 26.
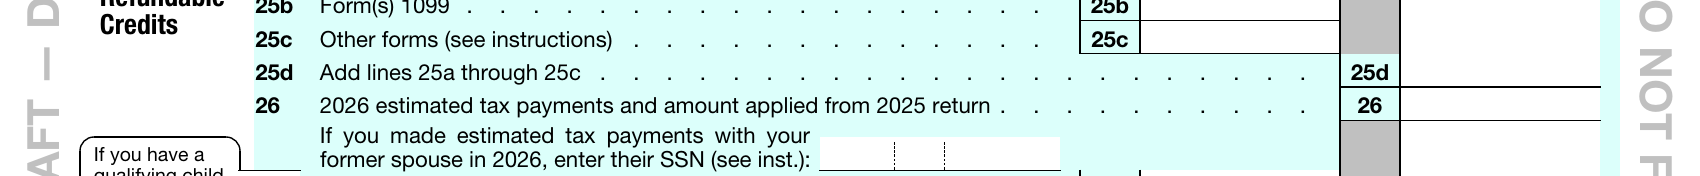
Read the line as the 2026 draft prints it: "2026 estimated tax payments and amount applied from 2025 return." Two sources of money share that line — payments you sent during the year, and any amount from a 2025 overpayment that was applied forward instead of refunded.
Be precise about what line 26 is not. It is not where the tax is computed. It is not a deduction. It is a payment credit — the return's record of money already sent. If the four payments in our example were all made, the amount entering at line 26 from those payments is $16,500 — four times $4,125 — plus any amount applied from the 2025 return, which in this example is zero.
And the status label matters: the Form 1040 cited here is the IRS draft posted September 17, 2026, labeled in this article as IRS draft as of October 6, 2026. When the final form posts, this page is re-read against it, and if the line moves, the change is recorded in a dated update note at the foot of this page — the old wording is never silently overwritten.
§7The January exception, read exactly
One exception is printed in Chapter 2 of Publication 505, and it is narrower than it is usually described.
It is not "the January payment is optional." It is this: if you file your 2026 Form 1040 and pay the remaining tax in full by January 31, 2027, you do not have to make the January 15, 2027 estimated payment.
Both halves have to happen — the return filed, and the balance paid, by January 31, 2027. File on February 2 instead, and the exception as printed does not describe your situation. The form of the rule is a filing deadline standing in for a payment deadline, and it only covers that fourth payment. It says nothing about April, June, or September, and it does not move any of those dates.
§8What this form does not cover
Form 1040-ES does not compute your business profit — that figure is built on Schedule C and reaches this worksheet only as the expected tax you supply to it. It does not cover state taxes. And it does not annualize anything: the worksheet's regular method is one division by four, and everything about uneven income lives on Form 2210, in a different article.
Software numbers vs ask-a-human numbers. The figures software can carry for this worksheet: the four due dates, the line 12 comparison, the division on line 15, and the total that has to show up at line 26 next spring. Numbers to take to a human before you act on them: whether the annualized method fits a year when closings all landed in one quarter, and whether a prior-year figure you are putting on line 12b is the figure that year's return actually shows.
That is the worksheet, as written, for 2026: a $1,000 test on line 14b, a smaller-of-two comparison on line 12, four equal payments from line 15 — April 15, June 15, September 15, 2026, and January 15, 2027 — and one landing line, Form 1040 line 26, IRS draft as of October 6, 2026.
Next article: Self-Employment Tax 2026 — Schedule SE, line 12. Article 2
Sources
8 claimsEvery claim above traces to a document, a tax year, a line, and the date it was checked.
-
1
Four due dates: Apr 15, Jun 15, Sep 15, 2026; Jan 15, 2027
- DOC
- Publication 505, Ch. 2 — Estimated Tax
- YEAR
- 2026
- LINE
- Ch. 2, due dates
- CHECKED
- 2026-10-06
-
2
$1,000 test: line 14b subtracts line 13 (income tax withheld only) from line 11c and asks whether the result is less than $1,000; refundable credits are subtracted earlier, at line 11b
- DOC
- Publication 505, Worksheet 2-1 (= Form 1040-ES worksheet)
- YEAR
- 2026
- LINE
- Lines 11b, 11c, 13, 14b
- CHECKED
- 2026-10-06; mapping corrected 2026-10-07
-
3
Required annual payment: smaller of 90% of 2026 tax or 100% of 2025 tax; 110% if 2025 AGI over $150,000 ($75,000 married filing separately)
- DOC
- Publication 505, Worksheet 2-1
- YEAR
- 2026
- LINE
- Lines 12a, 12b, 12c
- CHECKED
- 2026-10-06
-
4
Regular Installment Method: required annual payment divided into 4 equal installments on line 15; payment periods are 3, 2, 3, and 4 months of income, the payments are not unequal
- DOC
- Publication 505, Worksheet 2-1 / Ch. 2
- YEAR
- 2026
- LINE
- Lines 14a, 15
- CHECKED
- 2026-10-06; mapping corrected 2026-10-07
-
5
January exception: file the 2026 Form 1040 and pay the remaining tax in full by Jan 31, 2027, and the Jan 15, 2027 payment is not required
- DOC
- Publication 505, Ch. 2
- YEAR
- 2026
- LINE
- January payment exception
- CHECKED
- 2026-10-06
-
6
Estimated tax payments are claimed on Form 1040 line 26
- DOC
- Form 1040 (DRAFT), Rev. 2026, posted 09/17/2026
- YEAR
- 2026
- LINE
- Line 26, p. 2
- CHECKED
- 2026-10-06 — IRS draft as of 2026-10-06
-
7
Business income flows Schedule C line 31 → Schedule 1 line 3, Part I
- DOC
- Schedule C (DRAFT) / Schedule 1 (DRAFT, posted 06/08/2026)
- YEAR
- 2026
- LINE
- Schedule 1 line 3
- CHECKED
- 2026-10-06 — IRS draft as of 2026-10-06
-
8
Annualized method lives on Form 2210, Schedule AI; using Publication 505 Worksheet 2-9 to figure a payment means Form 2210 is filed with the return
- DOC
- Publication 505, Ch. 2; Form 2210 / Schedule AI
- YEAR
- 2026 (Pub. 505); Form 2210 instructions latest posted are the 2025 edition
- LINE
- Worksheet 2-9 note; Schedule AI
- CHECKED
- 2026-10-06
Update log
Changes are dated and kept. Old figures are never silently overwritten.