Freelance Taxes 2026: Designer & Consultant Schedule C, Line by Line
This is education, not tax advice. I'm not a CPA or EA. State taxes are not covered.
Schedule C, Schedule 1, and Schedule SE cited below are IRS draft as of 2026-10-07 — DRAFT, NOT FOR FILING. If a line changes, this page is updated in place with a dated note at the foot of the article.
- Last checked
- Tax year
- 2026
- Core line
- Schedule C, line 31 — net profit or
- Changes
- Update log (1)
§1One job, one tax year, one line
One job, one tax year, one line. The job is freelance designer and consultant — one person, billing clients directly. The year is 2026. The line is Schedule C, line 31: net profit or loss — the last line of the form, the number two other schedules are waiting for.
Article 5 walked this same form to line 31 for a real estate agent, on a realtor's expense set. This article walks it to the same bottom line for a designer and consultant, on a different expense set: contract labor and the Part V lines carry this job's walk. Client money in at line 1, the expense lines this job actually carries, a total at line 28, and the subtraction that produces line 31. Every expense in the example is named — when the walk ends, the bottom line is the example's own, not a partial one.
§2Where client money lands
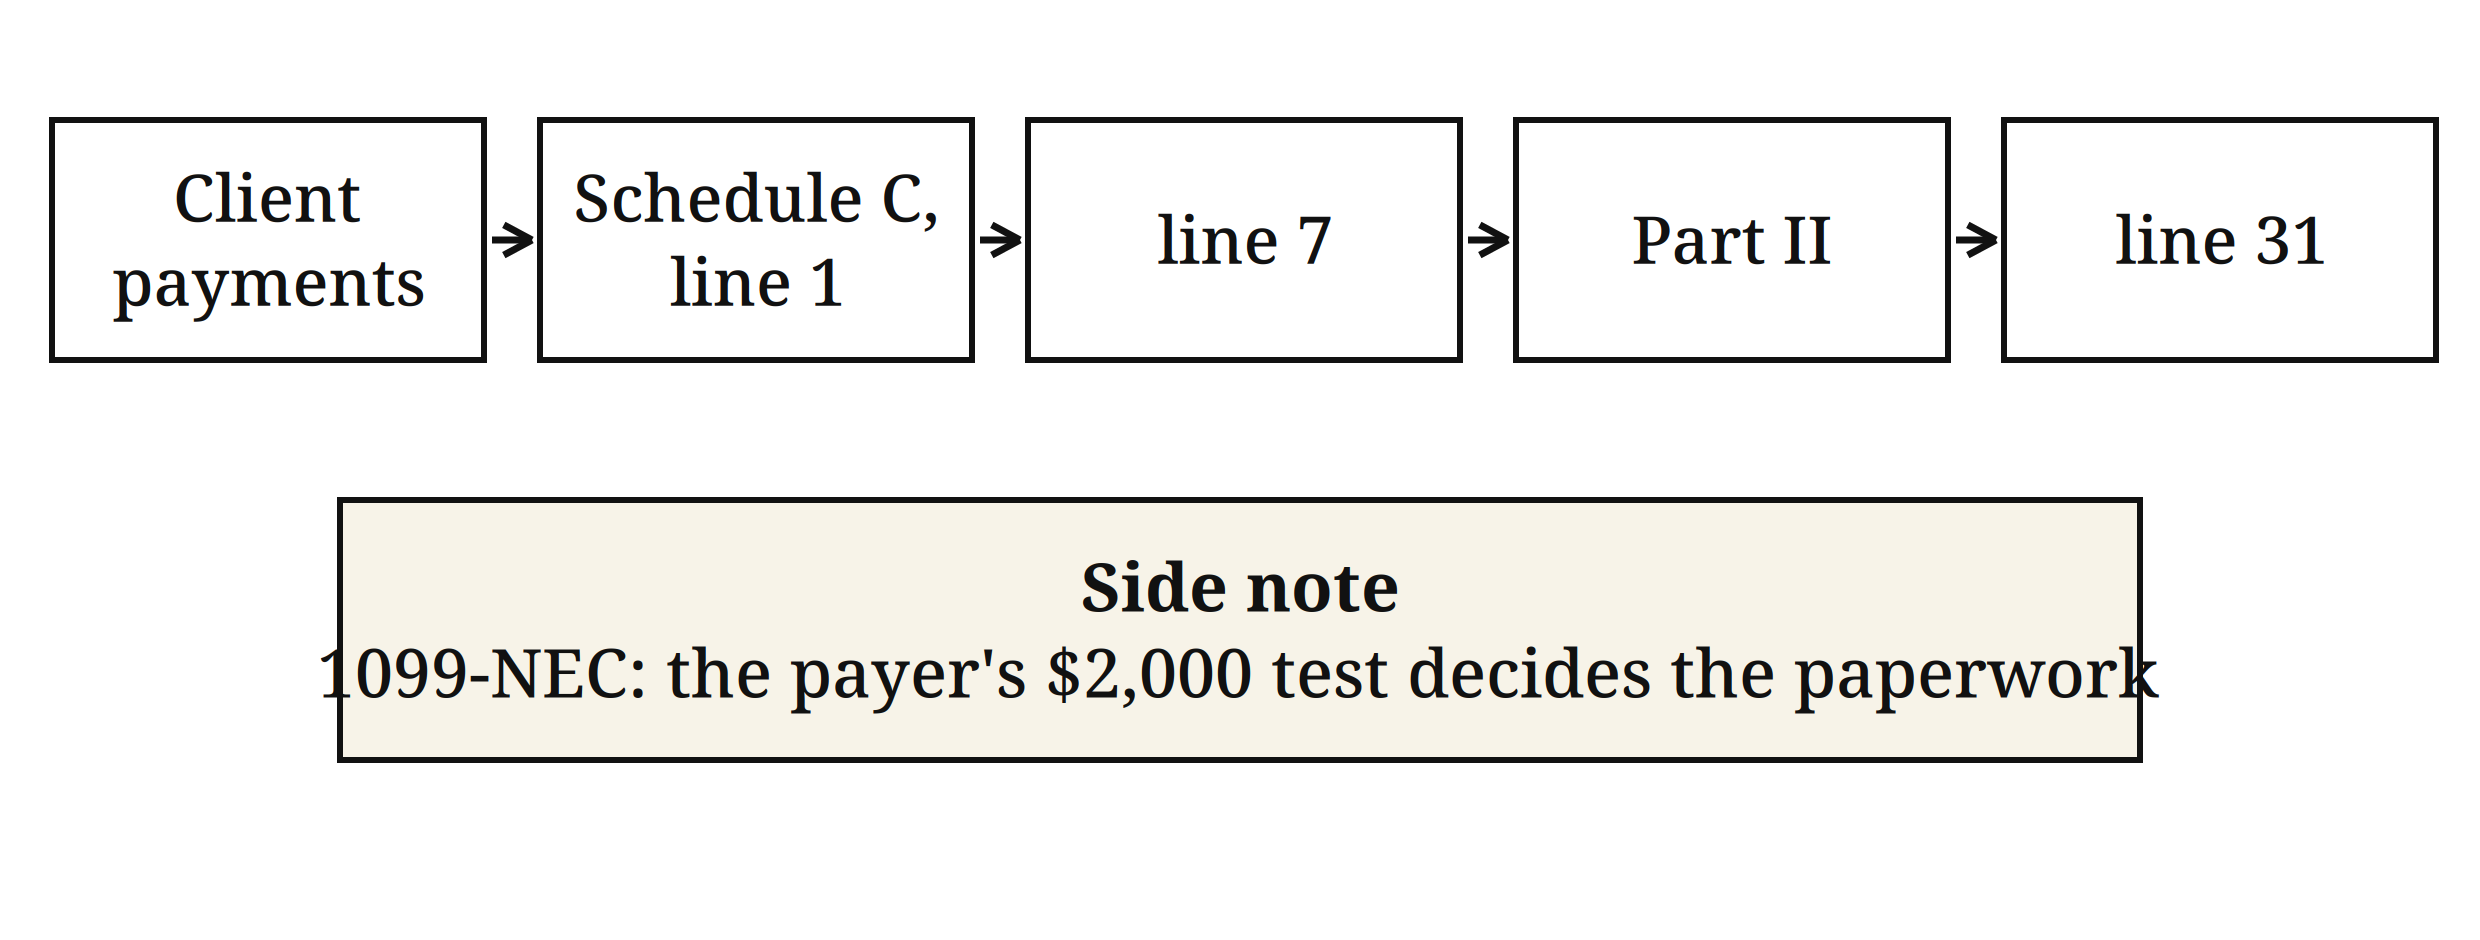
Client money first. A client who pays a designer or consultant for services reports it on Form 1099-NEC when the payer's test is met: nonemployee compensation of $2,000 or more in the year, under the conditions the payer's instructions list. A client who paid less than $2,000 generates no form.
Either way, the money lands in the same place. Line 1 of Schedule C is gross receipts or sales: the total of what the business took in from clients, with a form behind it or without one. The clients here pay the designer directly — no agency, no platform in between — so the paper trail, where there is one, is the clients' own forms. The $2,000 belongs to the payer's paperwork decision, and it will return in this article from the opposite direction — hold it in mind.
Below line 1, the form subtracts returns and allowances at line 2 and cost of goods sold at line 4, arriving at gross income on line 7. A design practice sells hours and judgment, not inventory, so this article's example keeps those lines at zero — read as the zeros they are; the real reading happens in Part II.
§3The expense lines this job carries
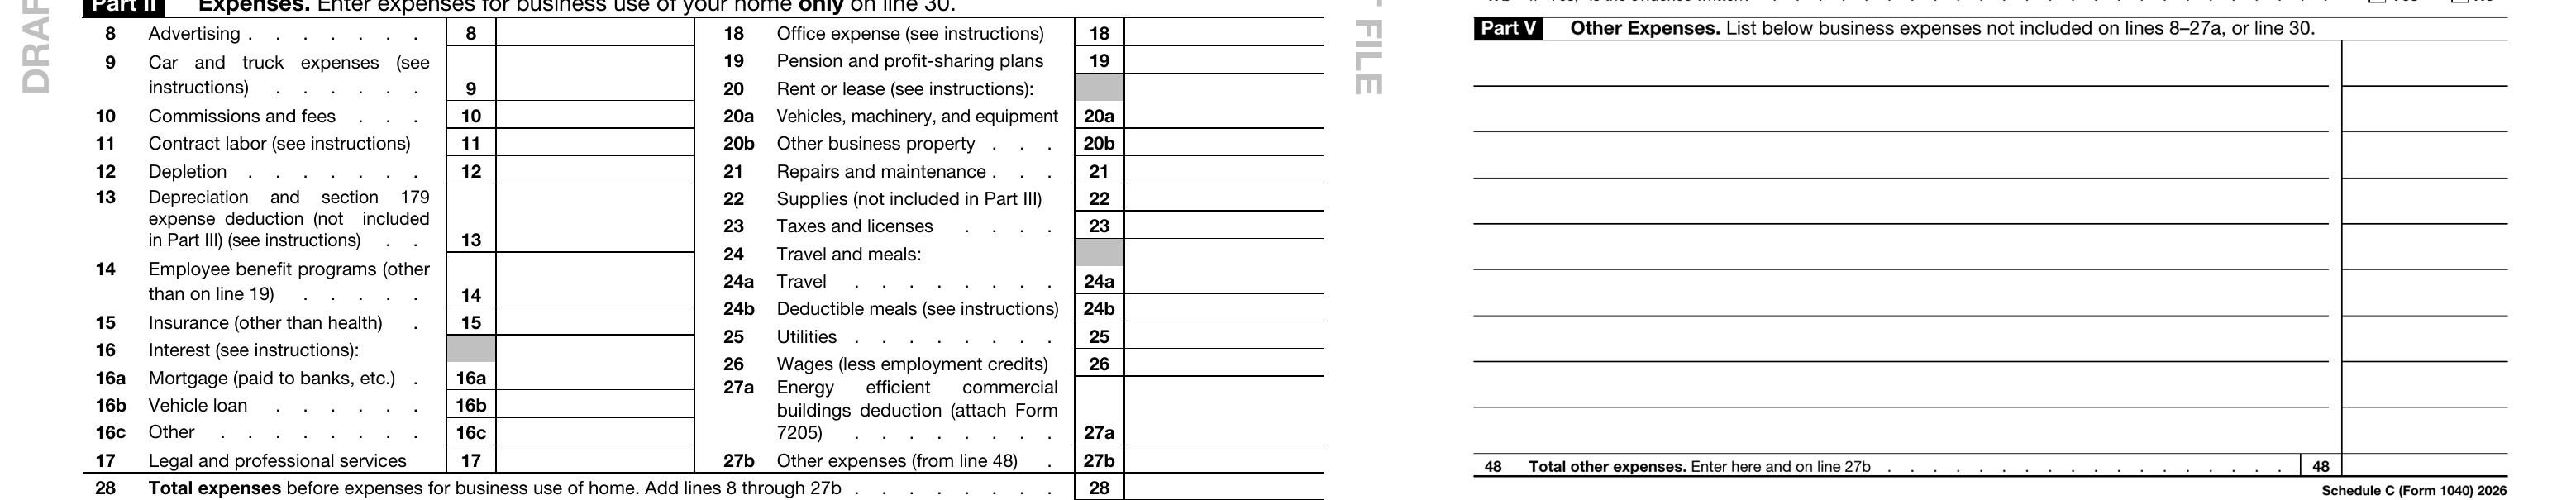
Part II is where this job's year actually shows up. Read the lines this work carries.
Line 11, contract labor: what the business pays other people to do work for it. A designer who hires a subcontractor — an illustrator, a developer — to deliver part of a client project reads that payment here. This is the line that makes the designer a payer, and the header of the form is about to ask about exactly that — the fork after the example returns to it.
Line 18, office expense: the cost of running the office side of the practice, on its own line, apart from supplies and apart from the home — the home has its own line, much further down, not read in this article.
Line 27b, other expenses, fed from line 48 in Part V: the form's listed-elsewhere line. Part V is where the business writes out what its other expenses are, item by item, and totals them at line 48. In this article's example, the job's software subscriptions are placed here — the design tools and services the practice pays for monthly, listed in Part V, totaled at line 48, carried to line 27b. That is the placement this example uses, and the worked example that follows is built on it.
Line 8, advertising, completes the set in this example. Four expense lines — 8, 11, 18, and 27b — are the whole expense side of the worked example that follows.
§4Worked example: $74,000 in, $61,024 at line 31
One worked example, with numbers used only in this article — and a closed set: the items named here are the only income and expense items in it.
A freelance designer and consultant — hypothetical — bills clients through 2026 and takes in $74,000. That total is line 1, gross receipts.
Line 2, returns and allowances: zero. Line 4, cost of goods sold: zero — nothing is stocked or resold. Line 6, other income: zero. So line 5 is $74,000, and line 7, gross income, is $74,000 — the entire income side, in this example, is the client total.
Part II, the four lines just read. Line 11, contract labor: $8,750 paid to a subcontractor across the year. Line 18, office expense: $1,850. Part V lists software subscriptions totaling $1,476; line 48 carries that total, and line 27b reads $1,476. Line 8, advertising: $900.
Line 28 totals the expense side — lines 8 through 27b. Add them: $900, plus $8,750, plus $1,850, plus $1,476. Line 28 is $12,976.
Line 29, tentative profit: line 7 minus line 28. $74,000 minus $12,976 is $61,024.
Line 30, expenses for business use of the home: zero in this example — deliberately. The home-office lines are an article of their own, and they are next; here line 30 is read as the zero it is, and nothing is estimated into it.
Line 31, net profit: line 29 minus line 30. $61,024 minus zero is $61,024. The core line of this article, reached, on a closed set of numbers.
| Step | Schedule C line | Operation | Amount |
|---|---|---|---|
| Client receipts (1099-NEC issued by each client who crossed that payer's $2,000 test; receipts total regardless of forms) | Line 1 | Hypothetical input | $74,000 |
| Returns and allowances | Line 2 | None in this example | $0 |
| Subtotal | Line 3 | Line 1 − line 2 | $74,000 |
| Cost of goods sold | Line 4 | None — no inventory | $0 |
| Gross profit | Line 5 | Line 3 − line 4 | $74,000 |
| Other income | Line 6 | None in this example | $0 |
| Gross income | Line 7 | Line 5 + line 6 | $74,000 |
| Advertising | Line 8 | Hypothetical input | $900 |
| Contract labor (subcontractor) | Line 11 | Hypothetical input | $8,750 |
| Office expense | Line 18 | Hypothetical input | $1,850 |
| Software subscriptions, listed in Part V → line 48 total | Line 27b (from line 48) | Part V items total | $1,476 |
| Total expenses before home | Line 28 | $900 + $8,750 + $1,850 + $1,476 | $12,976 |
| Tentative profit | Line 29 | Line 7 − line 28 ($74,000 − $12,976) | $61,024 |
| Business use of home | Line 30 | $0 in this article — Article 9's line | $0 |
| Net profit → Schedule 1, line 3 and Schedule SE, line 2 | Line 31 | Line 29 − line 30 ($61,024 − $0) | $61,024 |
§5The Fork: the same $2,000, from the other chair
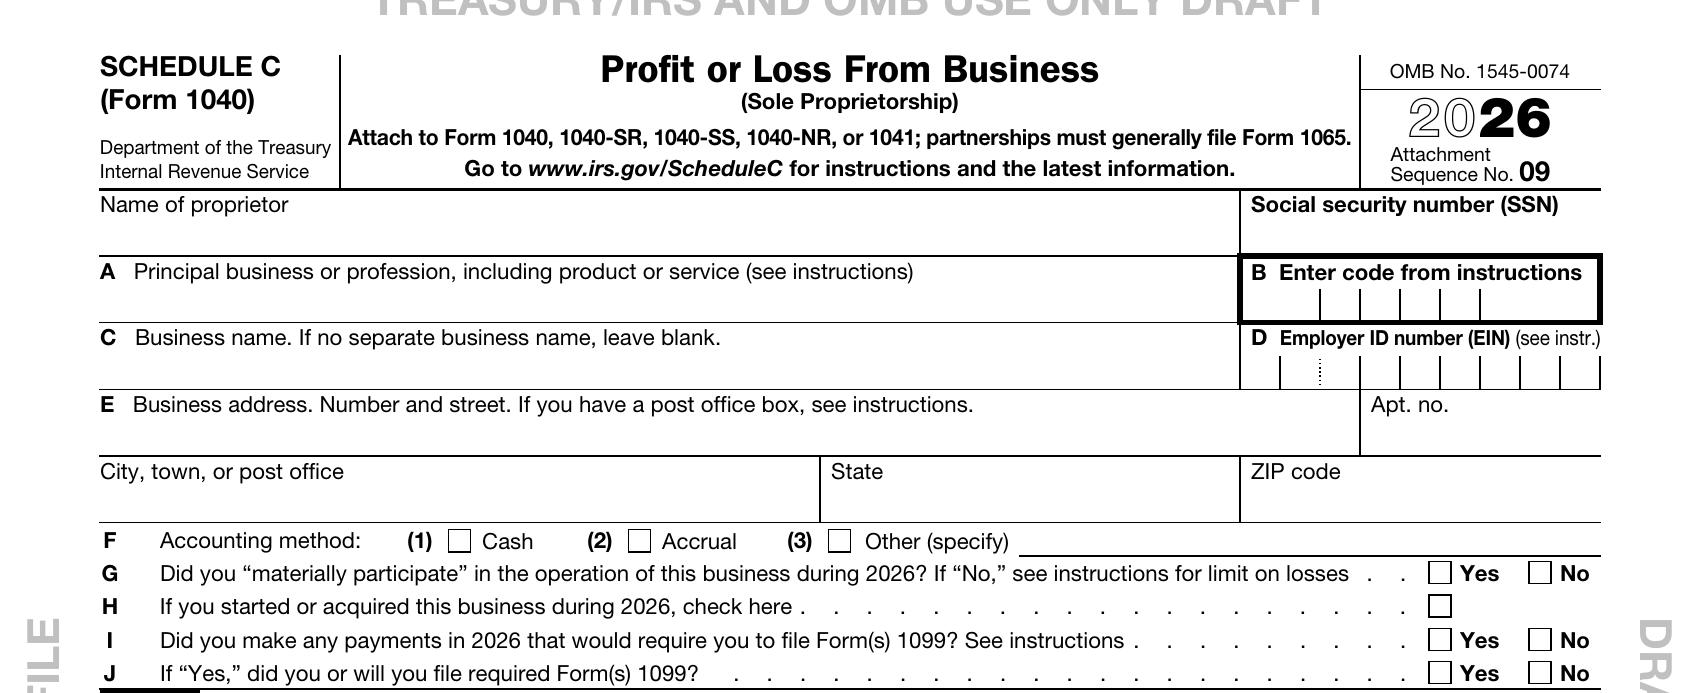
Schedule C (draft) header zoomed — items I and J highlighted. Split card below: left "As a recipient: a client's $2,000 decides whether a form arrives"; right "As a payer: your $2,000 to a subcontractor decides whether you issue one".
The fork is the threshold from the opening, seen from the other chair.
At the top of Schedule C, above Part I, the form's header asks two questions. Item I: did you make payments in 2026 that would require filing Forms 1099? Item J: if yes, did you or will you file them?
The example's line 11 is why those questions are on this form. The designer received $74,000 from clients — and paid $8,750 of it onward to a subcontractor. As a recipient, the designer's clients each measured their payments against $2,000: cross it, and a 1099-NEC arrives. As a payer, the designer measures the $8,750 against the same test, read from the payer's instructions: payments of $2,000 or more to a subcontractor in the year are the payments that reporting requirement is built on — and answering item I 'yes' while leaving item J undone is a state the form's own header puts in writing.
Same threshold, two directions, two documents: the payer's instructions decide whether a form is written; this form's header asks whether it was. Money in is reported about you; money out is reported by you.
§6Line 31's two landings
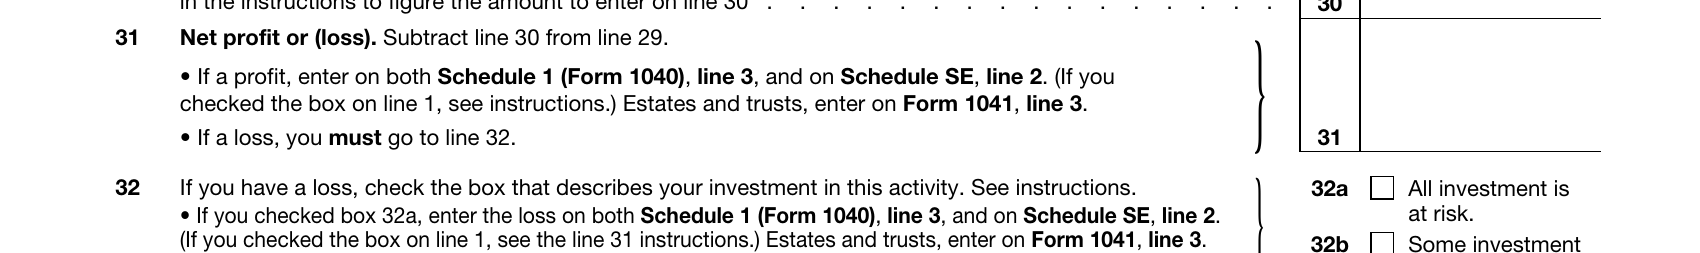
Where line 31 goes, because this form does not keep its own answer.
Line 31's printed text names two destinations. The first is Schedule 1, line 3 — business income or loss — in Part I of that schedule. The figure then runs through Schedule 1's own total at line 10, and it is line 10 that Form 1040 picks up, at its line 8 — whose caption reads 'Additional income from Schedule 1, line 10.' By that route the $61,024 joins the return's income: line 31 to Schedule 1 line 3, Schedule 1 line 10, Form 1040 line 8. The second is Schedule SE, line 2, where the same figure becomes the starting amount for the self-employment tax — a different form, a different tax, read line by line in this site's Schedule SE article, off this same line.
One number, figured once, read by two schedules for two purposes — which is why this article's core line is the bottom one: everything above it exists to make line 31 the number those two schedules can take.
§7What this form does not cover
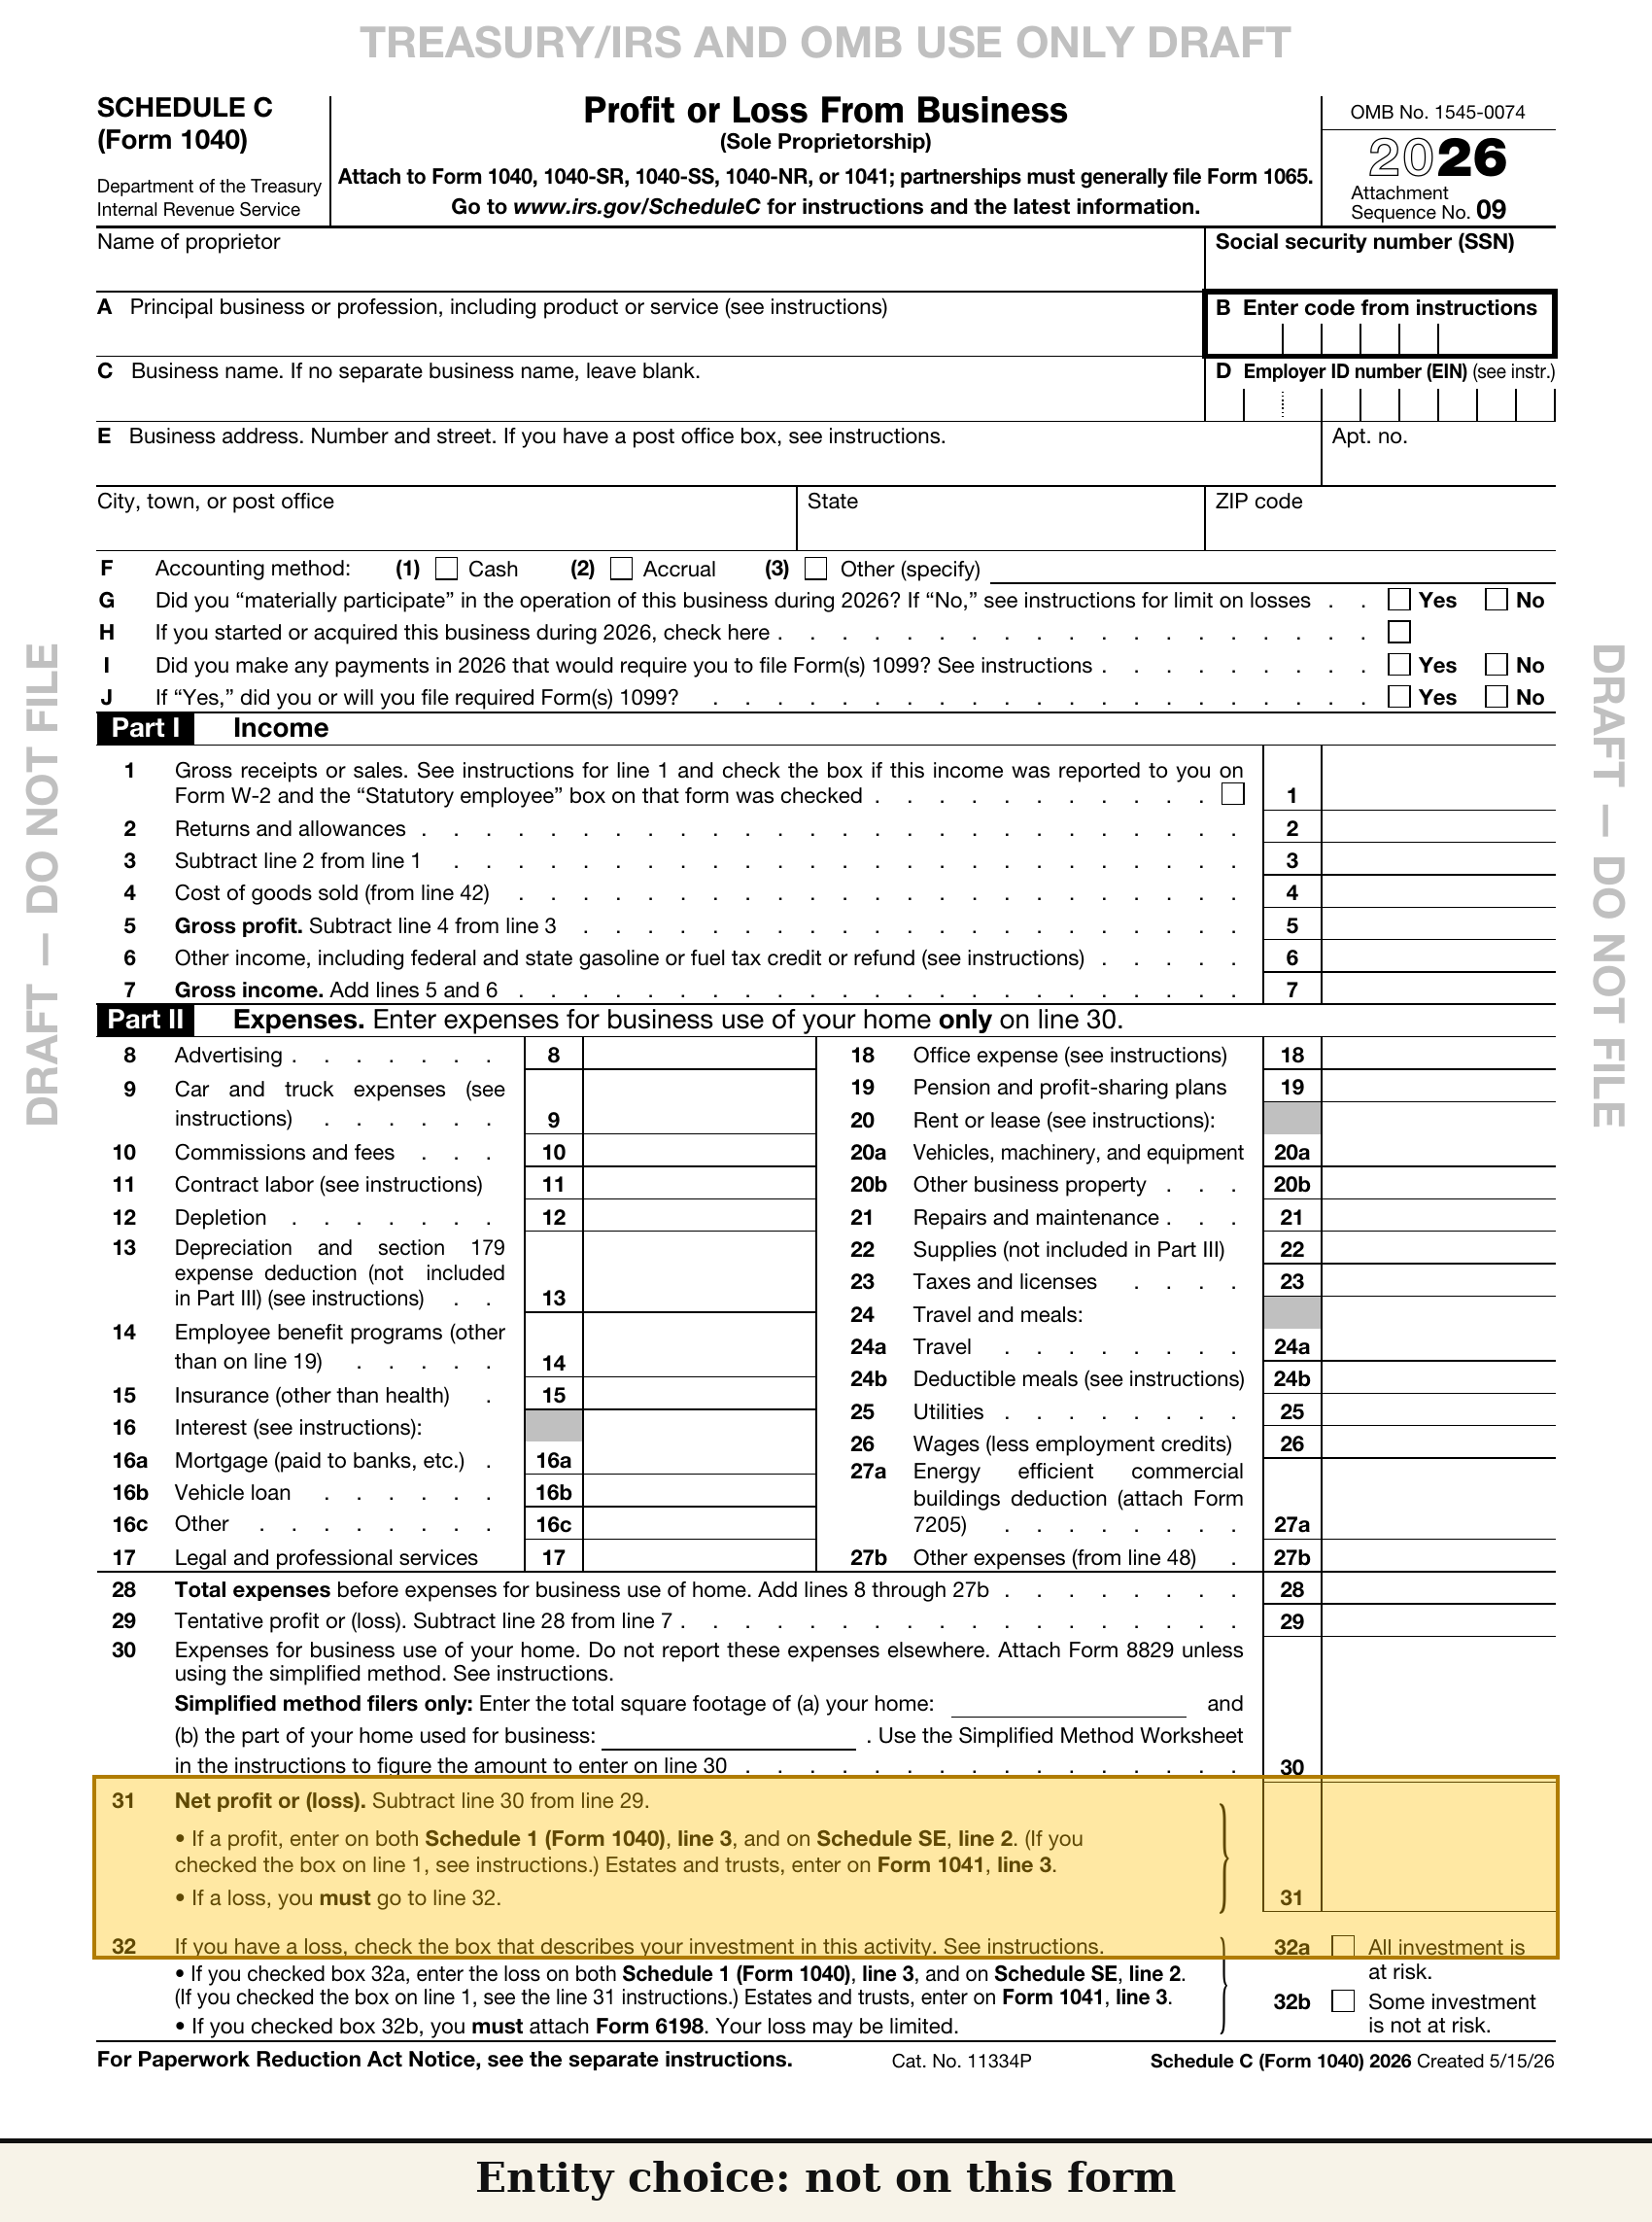
Schedule C full-page draft, greyed, with three callouts: "Entity choice: not on this form" / "Line 30 left at $0 here — Article 9" / "State taxes: not covered".
What this form does not cover, to close the reading.
It does not decide whether the work should run through a different entity — the form describes the business as it is; the election paperwork for a corporation lives on a different form. It does not figure the tax on the profit: line 31 is an input to other schedules, not a tax. It does not read the home: line 30 stood at zero throughout this article, and the two ways of figuring it — the simplified method and Form 8829 — are the next article's lines, not an afterthought to this one. And state taxes are not covered — not by this form as read here, and not by this site.
§8Software numbers vs ask-a-human numbers
Last, the division this walk has used from line 1 down: what the form's arithmetic settles once the inputs are fixed, and what it leaves open.
The arithmetic settles these: the line 28 total — $12,976 from the four lines read — the line 29 subtraction, and line 31 itself, $61,024, provided the inputs are the amounts the records and the payers' forms actually show.
What the arithmetic cannot settle goes to a human: whether a payment to a subcontractor required a form under item I in your year — the threshold is printed, but who counts as a contractor to be reported on is a classification question the header does not answer; what belongs in Part V when an expense could sit on two lines; and anything behind line 30, which this article left at zero on purpose.
That is the designer and consultant's Schedule C, as the draft prints it for 2026: $74,000 in at line 1, four expense lines totaling $12,976, and net profit of $61,024 at line 31. IRS draft as of October 7, 2026.
Next article: line 30 — the home office line this article left at zero, and the two methods that figure it. Article 9
Sources
6 claimsEvery claim above traces to a document, a tax year, a line, and the date it was checked.
-
1
A payer reports nonemployee compensation of $2,000 or more on Form 1099-NEC, box 1, under the four conditions the instructions list; under $2,000, no form is generated — the test is the payer's
- DOC
- Instructions for Forms 1099-MISC and 1099-NEC; Publication 1099 (2026)
- YEAR
- Rev. 12/2026; 2026
- LINE
- Box 1 reporting conditions
- CHECKED
- 2026-10-07
-
2
Schedule C Part I: line 1 gross receipts or sales; line 2 returns and allowances; line 3 = line 1 − line 2; line 4 cost of goods sold (from line 42); line 5 = line 3 − line 4; line 6 other income; line 7 gross income = line 5 + line 6
- DOC
- Schedule C (Form 1040) (2026 draft, posted 05/28/2026)
- YEAR
- 2026
- LINE
- Part I, lines 1–7
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
3
Schedule C Part II lines read for this job: line 8 advertising; line 11 contract labor; line 18 office expense; line 27b other expenses (from line 48); line 28 = total of lines 8 through 27b ("total expenses before home"); line 29 = line 7 − line 28; line 30 expenses for business use of your home; line 31 = line 29 − line 30
- DOC
- Schedule C (Form 1040) (2026 draft, posted 05/28/2026)
- YEAR
- 2026
- LINE
- Part II, lines 8, 11, 18, 27b, 28, 29, 30, 31
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
4
Part V, line 48: total other expenses, listed item by item in Part V and carried to line 27b
- DOC
- Schedule C (Form 1040) (2026 draft, posted 05/28/2026)
- YEAR
- 2026
- LINE
- Part V, line 48
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
5
Header items I and J: I — "did you make payments in 2026 that would require filing Form(s) 1099?"; J — if yes, did or will you file them
- DOC
- Schedule C (Form 1040) (2026 draft, posted 05/28/2026), header
- YEAR
- 2026
- LINE
- Header items I, J
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
6
Line 31's printed destinations: Schedule 1, line 3 ("Business income or (loss). Attach Schedule C") and Schedule SE, line 2, which cites "Schedule C, line 31"; Schedule 1's total at line 10 is picked up by Form 1040, line 8 ("Additional income from Schedule 1, line 10")
- DOC
- Schedule C (2026 draft), line 31 text; Schedule 1 (2026 draft, posted 06/08/2026), lines 3, 10; Schedule SE (2026 draft, posted 05/21/2026), line 2; Form 1040 (2026 draft), line 8
- YEAR
- 2026
- LINE
- Schedule C line 31; Schedule 1 lines 3, 10; Schedule SE line 2; Form 1040 line 8
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
Update log
Changes are dated and kept. Old figures are never silently overwritten.